Practical guidance for taxpayers and businesses facing IRS examinations, Appeals, Tax Court proceedings, collection matters, penalties, and criminal tax investigations.
Articles are provided for general informational purposes only and do not constitute legal advice.
Limited to conflicts, matter fit, and potential engagement. Substantive legal advice is provided only after engagement.
Washington, D.C. Office
800 Connecticut Avenue, N.W.
Suite 300
Washington, D.C. 20006
Secure video consultations are also available.
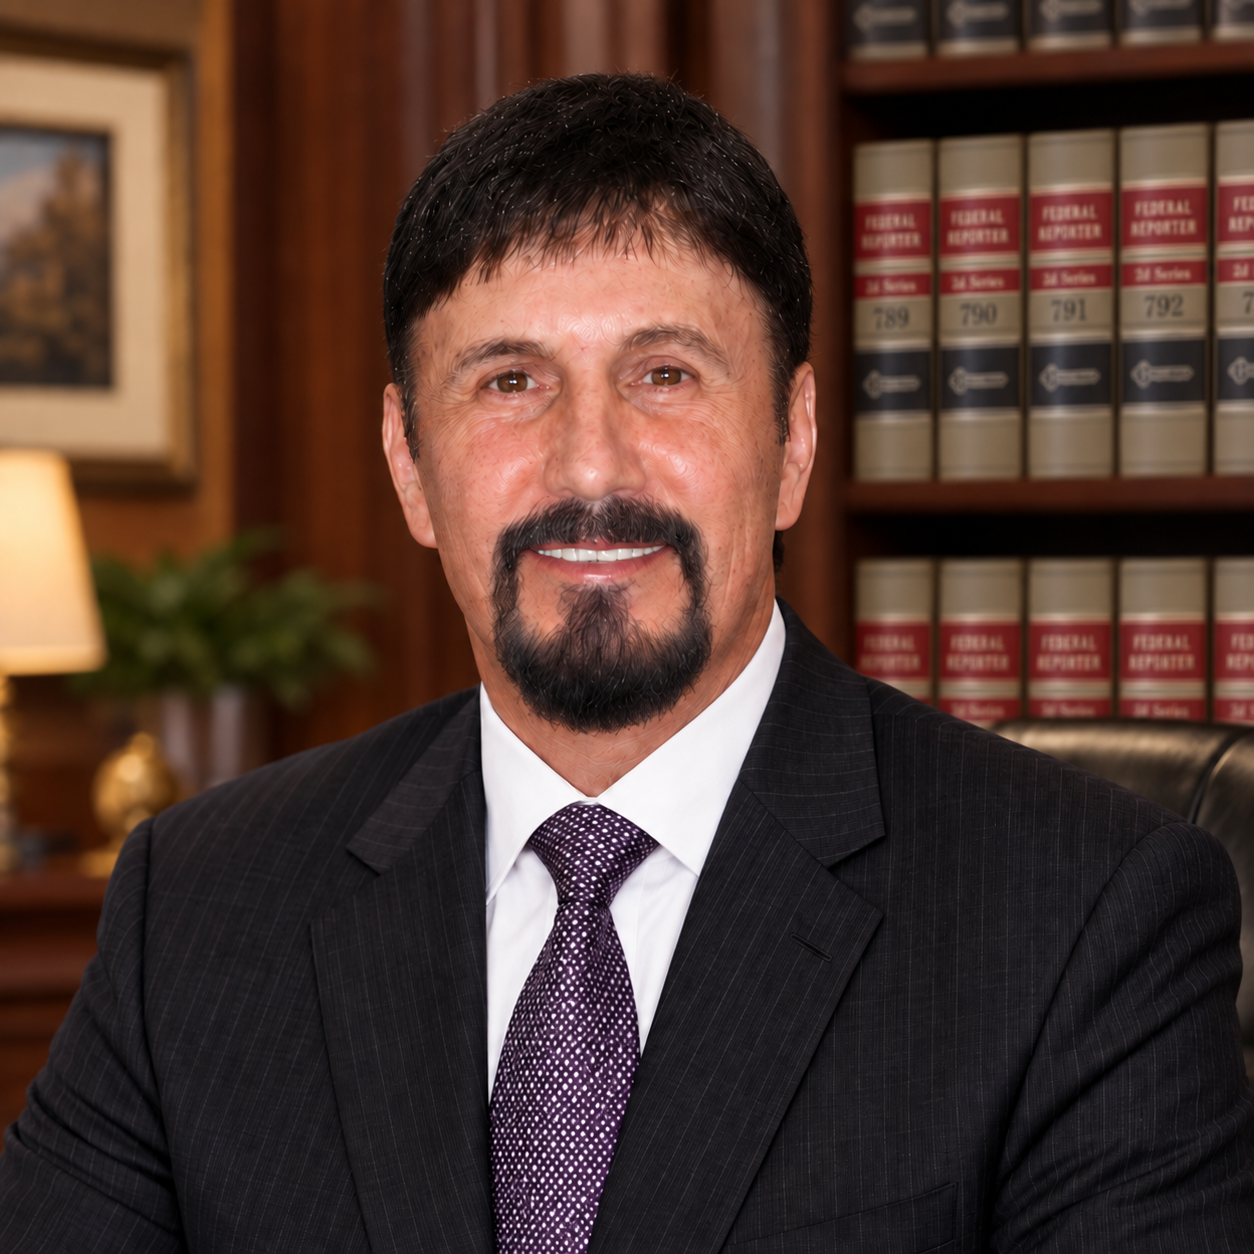
Attorney Chase Sizemore, JD, LLM
Principal, Chase Counsel PLLC
Georgetown Tax LLM | Former KPMG Auditor
U.S. Tax Court | Columbia University Graduate Studies
National Institute for Trial Advocacy (NITA) Diploma
30+ Years of Legal Experience
A first 48-hour decision guide for identifying the examination, reading the notice correctly, preserving the record, and deciding on representation before responding.
Read Article →A framework for deciding whether counsel is warranted, organized around the nature of the dispute rather than the size of the number.
Read Article →Both can represent you before the IRS. The question is what the dispute actually turns on, and whether privilege matters.
Read Article →What drives the number, how fees are structured at each stage of a controversy, and why comparing hourly rates is usually the wrong comparison.
Read Article →The roadmap from an examination report to the IRS Independent Office of Appeals, what a written protest must actually contain, and what happens if Appeals does not resolve the case.
Read Article →A procedural walkthrough of an Appeals matter, from receipt of the case through the conference to the closing agreement, and what actually distinguishes Appeals from Examination.
Read Article →The statutory notice of deficiency, the petition period it starts, what the notice does and does not mean, and the documents to gather immediately.
Read Article →What actually occurs procedurally after a missed deficiency petition, which alternative routes exist, what each of them requires, and why none is a substitute for a timely petition.
Read Article →What Tax Court representation actually consists of, stage by stage, and why trial experience is the wrong proxy for competence in a forum where most cases settle.
Read Article →What a levy is, the notices that must precede it, the 21-day window that determines whether the money is recoverable, and what to do the day you learn of one.
Read Article →Why the first interview is the decision that matters, what distinguishes a criminal investigation from an examination, and where the protections you assume you have do not exist.
Read Article →The lifecycle of a criminal tax matter from initiation through prosecution or declination, the review layers most people do not know exist, and why early decisions can shape the case.
Read Article →A practitioner-focused guide to developing the factual record, preserving legal arguments, presenting authorities, and framing the hazards of litigation before the IRS Independent Office of Appeals.
Read Article →An examination of personal liability for unpaid employment taxes, Fourth Circuit standards for responsibility and willfulness, IRS assessment procedures, limitations periods, payment credits, and federal court litigation.
Read Article →A practitioner-focused analysis of §6038A penalty disputes, including reasonable cause, the small-corporation rule, systemically assessed PRN 711 penalties, IRS Appeals, Collection Due Process consequences, and refund litigation.
Read Article →A practical guide to defending an IRS cryptocurrency examination, including basis reconstruction, Form 1099-DA reporting, wallet tracing, staking and DeFi issues, penalties, statutes of limitation, and procedural defenses.
Read Article →Choose the option that works best for you.
Call to discuss an IRS examination, Appeals matter, Tax Court proceeding, collection issue, criminal tax matter, or related federal tax controversy.
Call (703) 403-1488Reserve a complimentary 30-minute Zoom screening to discuss a federal tax controversy matter and possible next steps.
Schedule a Zoom CallSend preliminary, nonconfidential information about a federal tax controversy matter for review, and we will follow up.
Start a Written Inquiry